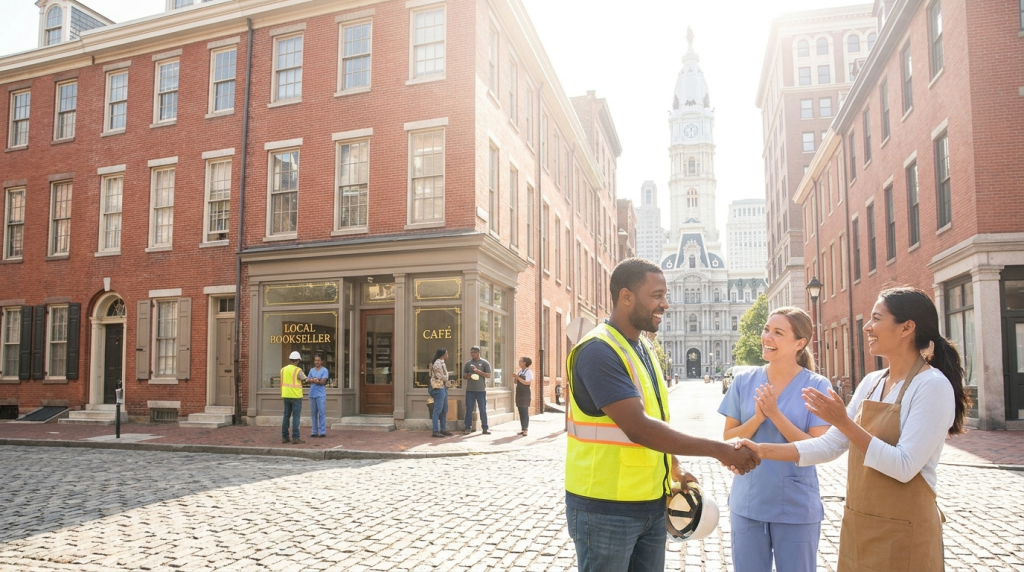
Philadelphia voters have approved PhillySaves, the nation’s first city-run automatic individual retirement account program for workers without employer-sponsored plans. The ballot measure seeks to expand retirement saving among employees who lack access through their jobs.
The vote puts Philadelphia at the front of a new local policy experiment. States have created similar automatic IRA programs, but PhillySaves shifts that model to city government. Its success could influence other cities facing gaps in workplace retirement coverage.
Table of Contents
ToggleHow PhillySaves Changes Workplace Saving
Automatic IRA programs generally require covered employers to help workers enroll in individual retirement accounts. Employees can usually opt out, while participating workers contribute through payroll deductions.
PhillySaves is designed for workers whose employers do not offer retirement plans. That focus addresses a basic problem: Saving is harder when employees must open accounts and arrange deposits on their own.
Automatic enrollment changes the default. Instead of asking workers to take several steps before saving, it places them on a path to participate. They may still decide that the program does not fit their needs.
The measure’s central promise can be summed up in its defining description:
“The nation’s first city-run auto-IRA program for workers lacking employer retirement plans.”
That first-of-its-kind status also brings pressure. Philadelphia must show that a city can administer the program clearly, protect participants and avoid placing needless strain on employers.
Why Access Matters
Workplace retirement plans make saving easier because contributions occur with each paycheck. Workers without that option often face more paperwork, more decisions and fewer reminders to save.
PhillySaves targets that access gap rather than guaranteeing a specific retirement outcome. An IRA can help workers build personal savings, but account balances still depend on contributions, investment performance, fees and time.
The policy could be especially relevant to people working for smaller businesses that do not sponsor retirement benefits. However, the ballot measure alone does not erase financial pressure. Lower-paid workers may struggle to contribute while covering rent, food and other immediate expenses.
- Workers gain a payroll-based route to retirement saving.
- Employers without plans may receive new administrative duties.
- City officials must explain enrollment, opt-out rules and account oversight.
Implementation Will Be the Real Test
Approval is only the opening step. The city will need to establish operating rules, timelines and systems for employers and employees. Public education will also matter because an unfamiliar deduction can produce confusion, especially if notices are unclear.
Supporters can point to the convenience of automatic saving and the expanded access for uncovered workers. Critics and cautious employers may focus on compliance costs, recordkeeping and the city’s ability to manage a financial program.
Those concerns do not cancel the program’s goal, but they shape how Philadelphia should proceed. A smooth launch will require simple instructions, accessible opt-out procedures and clear lines of responsibility.
Officials will also need to track results. Useful measures include employer participation, worker enrollment, opt-out rates and average contributions. Fee levels and complaints will offer another test of whether the program works as intended.
A Local Model With National Stakes
PhillySaves expands the retirement policy debate from states to cities. If Philadelphia can enroll uncovered workers without creating heavy administrative problems, other large municipalities may consider similar measures.
A troubled rollout could have the opposite effect. Delays, unclear charges or weak participation would give skeptics reasons to question whether cities are suited to this role.
Philadelphia has now made the policy choice. The next phase will determine whether PhillySaves becomes a practical savings tool or merely a clever name on a ballot. Workers, employers and other cities will be watching the implementation closely.