Entrepreneurs always have a “number” in mind.
At the beginning of my career, I believed that reaching a certain net worth or revenue threshold would unlock complete peace of mind. Once I reached the summit, I promised myself I would stop worrying late at night and checking my bank balances endlessly. As a founder, investor, or executive, you probably have told yourself the same story.
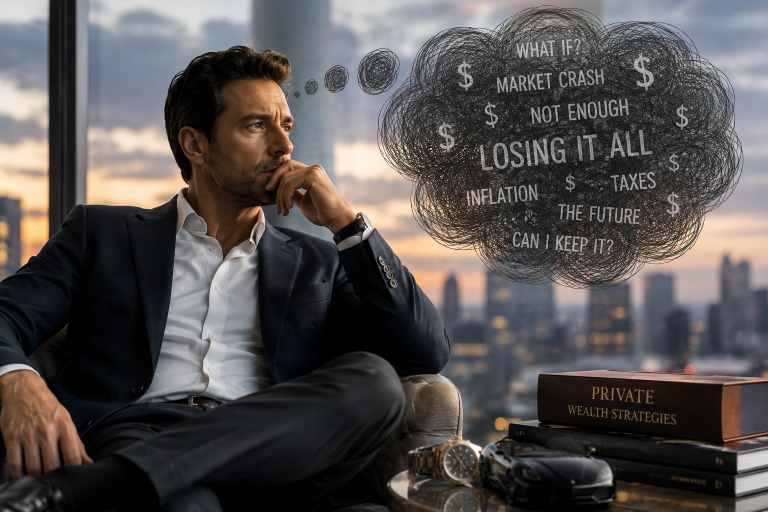
But here’s the uncomfortable truth few successful people talk about publicly: wealth doesn’t eliminate money anxiety—it simply shifts its focus.
According to a survey of 1,875 U.S. adults by investing app Acorns, financial anxiety does not decrease with income levels. 51% of respondents earning less than $20,000 per year reported feeling financially anxious, while 46% reported feeling the same way. The data also show that respondents could ease their minds by having a higher net worth. In fact, 65% of Americans with negative net worth said they were experiencing financial anxiety. This compares with 43% of those with no debt and assets, and 47% of those with a net worth between $75,000 and $250,000.
However, even a significant net worth doesn’t eliminate psychological dread, as many high-earners realize. True financial peace comes from understanding why money anxiety survives wealth — and what you can do to end it.
The Moving Goalpost and “Income Hedonics”
Why don’t we feel safer when we make more money? The data show that simply increasing your top-line earnings has little impact on financial stress. Financial anxiety is rarely an arithmetic issue; it is a psychological one.
As your income rises, two powerful psychological phenomena take root: hedonic adaptation and lifestyle creep.
As soon as you cross an income threshold, your brain recalibrates itself to recognize a new baseline as normal. The elevated lifestyle, such as a large home, private schooling, aggressive reinvestment, and high monthly operational expenses, stops feeling like a luxury and becomes a necessity.
Since fixed overhead often climbs along with top-line earnings, an entrepreneur making $500,000 a year often feels just as financially vulnerable as one who makes $50,000. As soon as your baseline shifts, your margin for perceived error shrinks back to its original size.
Moreover, money anxiety is strongly associated with “money scripts” — unconscious beliefs about money that are forged early in life. When you built your company under constant threat of payroll failure or bankruptcy, your nervous system became hypervigilant. The fact that you earn ten times more money does not automatically rewrite those mental programs. Even though the immediate threat has passed, the internal alarm system remains fully operational.
Inside the Minds of the Ultra-Rich: What They Actually Fear
If you think that money anxiety disappears when you have a multimillion-dollar net worth, take a look at the ultra-high-net-worth tier. According to Kiplinger, having vast fortunes creates an entirely new category of complex, high-stakes anxieties for the ultra-rich.
While ultra-wealthy people enjoy effortless security, they face distinct structural fears.
The asset-rich, cash-poor trap.
Most founders and real estate moguls have net worths in the millions, but little cash liquidity. They hold most of their wealth in private equity, commercial real estate, and highly concentrated stock positions. During market downturns, tax obligations, or sudden capital calls, these individuals may face acute liquidity challenges. Regardless of your balance sheet total, a lack of immediate liquidity creates intense panic in the upper echelons of business.
Regulatory and tax volatility.
When you reach a certain level of wealth, tax planning becomes a constant risk-management challenge. You can’t predict how an international tax law change or a single policy proposal in Washington can affect a lifetime of legacy building. It’s not just paying taxes that scares people; it’s the unpredictability of shifting rules that dismantle carefully constructed structures.
The generational wealth dilemma.
The anxiety associated with legacy anxiety is very real for founders who sacrificed decades to build an enterprise. The fear of passing wealth down to your children triggers complex questions, such as;
- Will my kids lose their drive?
- What will happen if inheritance fractures family unity?
- Can my heirs manage these assets effectively?
In short, rather than bringing security to families, wealth can often cause tension.
Geopolitical risk and visibility.
Global market exposure means global vulnerability. Beyond currency fluctuations, geopolitical conflicts, supply chain shocks, and cyber threats can directly affect high-net-worth portfolios. Furthermore, prominent wealth is now a target of litigation, scrutiny, and public condemnation in today’s hyper-connected world.
The Entrepreneurial Identity Dilemma
The blurring of net worth and self-worth adds another layer of psychological complexity for business owners.
As entrepreneurs, we’re conditioned to view numbers as scorecards. Beyond monthly recurring revenue (MRR), gross margins, and EBITDA multiples, we also track net asset values. When your company grows, you feel invincible; when growth stalls or macro conditions shift, you feel existentially threatened.
Often, entrepreneurs mistake risk tolerance for risk immunity since they are comfortable taking operational risks. In reality, carrying the future of your family, the expectations of your employees, and your employees’ livelihoods creates chronic cognitive strain. It’s not just about managing money; it’s about managing responsibility, too. Until you decouple your identity from your balance sheet, no financial windfall will ever feel sufficient.
How to Build True Financial Peace
What can cure money anxiety if wealth alone isn’t enough? In my years of building businesses, investing, and advising founders, I’ve learned that financial tranquility requires intentional mindset shifts.
Audit your money scripts.
Identify the source of your financial fear. Are you making scarcity-based decisions because of an early business failure or childhood insecurity? You can distinguish real operational threats from phantom anxiety by identifying the emotional drivers behind your financial behavior.
Define “enough.”
Unless you have a clear, static definition of what “enough” looks like, your brain will keep shifting the goalposts. Lock in your personal financial baseline, including expenses, security, and freedom. Once you reach that metric, additional accumulation becomes secondary.
Prioritize liquidity and optionality.
Avoid becoming asset-rich while cash-poor. Keep a dedicated, high-liquidity reserve separate from your business operations and volatile investments. Having 12 to 24 months of runway liquid and accessible provides a psychological buffer that illiquid equity cannot.
Separate self-worth from net worth.
Business is an asset you operate, not an extension of who you are. Develop your identity, relationships, and interests independent of your company’s valuation. Unless your self-esteem is tied to yesterday’s closing price or quarterly revenues, market swings cannot dismantle your mental health.
The Bottom Line
Having wealth buys you options, access, and freedom from basic material strains. However, it does not-and cannot-buy freedom from anxiety.
Spending your career chasing an arbitrary bank balance in the hope that it will finally make you feel safe will always leave you disappointed. It takes emotional self-awareness, clear boundaries, and the realization that security comes from within, not from your dashboard, to achieve true financial peace.
Image Credit: Albert Costill/ChatGPT