A major stock index can sit near a record while many of its members struggle. That split deserves attention. It doesn’t guarantee a crash, but it can reveal hidden weakness and a growing dependence on a small group of large technology companies.
I am Taylor Sohns, CEO of LifeGoal Wealth Advisors, a Certified Investment Management Analyst and Certified Financial Planner. I oversee more than $500 million in client assets. From that perspective, market concentration is a risk signal worth studying, not predicting.
Table of Contents
ToggleA Rare Warning From Market History
The S&P 500 has rarely traded within 1% of an all-time high while more stocks reached 52-week lows than 52-week highs. This unusual condition has appeared only three times in the historical record.
- July 1929, before the Great Depression and an eventual 86% market drawdown.
- January 1973, near the oil embargo and a 48% drawdown.
- December 1999, near the end of the dot-com boom and a 49% decline.
These examples are alarming because each occurred near a major market peak. Still, history is a guide, not a fixed script. Three observations aren’t enough to establish a dependable forecasting rule.
The economic setting also differed in each case. The 1929 decline stemmed from financial instability and a deep economic contraction. The 1970s brought an oil shock, inflation, and slower growth. The dot-com decline followed extreme valuations in internet and technology shares.
Today’s conditions have their own features. Large technology businesses often produce substantial revenue, profits, and cash flow. Many leading companies are stronger than the speculative firms that dominated attention in 1999. That distinction matters, even if prices and investor expectations still create risk.
“There’s carnage beneath the surface today, with more stocks hitting new lows than new highs, but big tech is keeping the market afloat.”
View this post on Instagram
Why Index Records Can Hide Weakness
The S&P 500 is market-cap weighted. A company with a larger total stock value has more influence on the index than a smaller company. As a result, gains in a few giant businesses can offset losses across many other stocks.
Imagine that several of the largest technology companies rise sharply while hundreds of smaller index members remain flat or fall. The headline index could still post a gain. An investor looking only at that headline might assume most companies are doing well.
Market breadth helps correct that impression. Breadth measures participation across individual stocks. One simple comparison counts how many companies are reaching 52-week highs and how many are reaching 52-week lows.
Healthy participation usually means gains are spread across many businesses and industries. Narrow participation means fewer companies drive most index progress. The latter can make the market more sensitive to disappointing news from its leaders.
This does not mean concentrated markets must fall. Leadership can remain narrow for long periods. Strong companies may continue gaining market share, increasing earnings, and attracting investor capital. The concern is that the index becomes dependent on those companies meeting very high expectations.
The Risks of Heavy Big Tech Leadership
Big Technology companies carry unusual weight in major indexes. Their size means even modest price movements can shift the entire market. That influence works both ways.
If leading companies report better sales, rising profits, or strong demand, their shares can support the index. If results fall short, losses may spread quickly because many portfolios own the same market leaders.
Three questions deserve close attention:
- Can earnings grow fast enough to support current share prices?
- Can these companies fund large investments as borrowing costs rise?
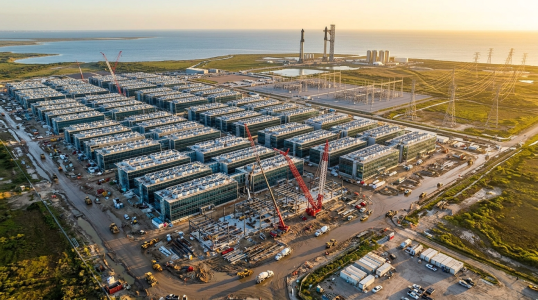
- Will public resistance slow the construction of power-hungry data centers?
Valuation is part of this discussion. A strong business can still be a poor investment if its stock price assumes near-perfect results. Higher valuations give companies less room for errors, delays, or weaker forecasts.
Concentration also creates portfolio risk outside the index itself. Investors may own an S&P 500 fund, a technology fund, and several individual technology stocks. Those holdings can look diversified on an account statement while relying on many of the same companies.
How Higher Interest Rates Affect Market Leaders
The federal funds rate influences financing costs across the economy. If that rate stays high or moves higher, borrowing often becomes more expensive for businesses and consumers.
Large technology companies may have strong balance sheets, but higher rates don’t insulate them. Their customers can reduce spending. Corporate clients may delay software projects, advertising plans, or equipment purchases. Consumers may also become more selective.
Interest rates can also affect stock valuations. Investors estimate what a company’s future earnings are worth today. Higher rates can reduce the present value assigned to profits expected many years from now.
That issue often matters more for growth stocks. Much of their value is based on future expansion. If investors apply a higher discount rate to those future profits, share prices can still come under pressure even if the business remains sound.
Financing large data centers adds another concern. Artificial intelligence services require chips, cooling systems, buildings, and vast amounts of electricity. Large firms can cover much of this spending with cash flow, but the scale still pressures budgets and expected returns.
Public Resistance to Data Centers
Data centers are central to cloud computing and artificial intelligence. They also raise local concerns about energy use, water demand, land use, noise, and utility costs.
Communities may support technology investment while questioning how projects affect local resources. Permit delays, power connections, and construction could slow planned growth. Higher operating costs could also reduce profit margins.
Investors should watch how technology companies address these concerns. Key questions include how much they are spending, how quickly new facilities will start generating revenue, and whether energy supply can meet demand.
Public opposition does not mean the data-center expansion will stop. It does mean growth plans may face practical limits. Forecasts based on rapid construction should account for those limits.
Why Earnings Reports Matter
Big Tech earnings directly test the market’s assumptions. Share prices may reflect confidence about artificial intelligence, cloud services, digital advertising, and consumer demand. Financial reports show whether those expectations are translating into revenue and profit.
I would focus on several measures rather than the headline earnings number alone:
- Revenue growth across core business lines.
- Profit margins after technology and infrastructure spending.
- Capital spending on chips, networks, and data centers.
- Management forecasts for future sales and expenses.
- Cash flow available after major investments.
- Evidence that artificial intelligence spending is producing revenue.
Management guidance can matter as much as past results. A company might beat estimates for the latest quarter but warn of slower demand ahead. It might also report heavy spending without giving investors a clear path to future returns.
The market’s reaction provides another clue. A strong report followed by a falling share price may suggest that expectations were already too high. A modest report followed by gains may mean investors had prepared for worse.
A Warning Signal Is Not a Forecast
I am not forecasting a 50% market decline. Such an outcome is possible in financial markets, but one breadth measure does not imply it as the base case.
The historical record should encourage caution, not panic. The sample includes only three prior periods. Each was followed by a severe loss, yet that does not prove the same result must happen again.
Investors can use the signal to review risk. That may include checking stock exposure, identifying repeated holdings across funds, and confirming that the portfolio still matches the investor’s time horizon.
Long-term investors should also avoid abrupt decisions based on one statistic. Selling everything after a warning can create a second problem: deciding when to return. Missing a recovery can damage long-term results.
A more measured response may include rebalancing, maintaining suitable cash reserves, and spreading investments across sectors, company sizes, and asset types. The right action depends on personal goals, tax issues, income needs, and tolerance for losses.
What Investors Should Watch Next
Market breadth remains an important measure. More stocks reaching new highs would suggest wider participation. Continued weakness beneath the index would show that leadership remains narrow.
Interest-rate policy also matters. Investors should monitor inflation, economic growth, and Federal Reserve statements. These factors may shape borrowing costs and stock valuations.
Big Tech earnings will help answer the most immediate question: Can a small group of very large companies keep carrying the index? Strong results may extend that leadership. Weak forecasts or disappointing returns on spending could test investor confidence.
The central lesson is simple. An index near a record does not mean the whole market is healthy. Investors should look beneath the headline, study participation, and understand how much performance depends on a few stocks.
History supports careful review, but not a rushed retreat. A disciplined plan should account for concentration, rates, earnings, and personal financial needs. Those factors provide a sounder basis for decisions than either fear or enthusiasm alone.
Frequently Asked Questions
Q: What does market concentration mean?
Market concentration means a small number of large companies account for a large share of an index’s value and performance. This can make the index more dependent on those companies.
Q: Does weak market breadth predict an immediate crash?
No. Weak breadth can signal limited participation and higher risk, but it cannot reliably predict the timing or size of a decline. Review it alongside earnings, valuations, rates, and economic data.
Q: How can investors respond to a concentrated market?
Investors can review repeated exposure across funds, rebalance if needed, and confirm that their mix fits their goals. Major changes should reflect a financial plan rather than one historical indicator.