Table of Contents
ToggleKey Takeaways
- Envelope budgeting divides your spending money into category “envelopes”; when an envelope is empty, you stop spending in that category.
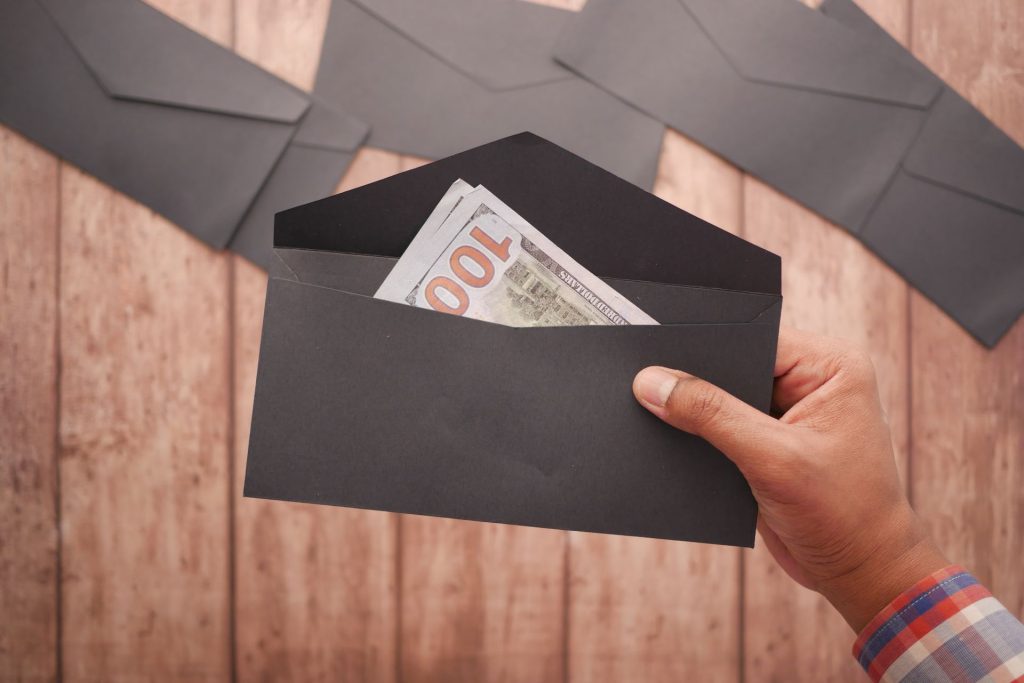
- “Cash stuffing” is the viral, literal version—physically putting cash into labeled envelopes.
- It works because it makes spending tangible and enforces hard limits, which curbs overspending.
- The main drawbacks are the hassle of cash and security risk; digital envelope systems solve both.
Envelope budgeting is a method where you divide your monthly spending money into separate “envelopes” by category—groceries, dining, gas, entertainment—and once an envelope is empty, you stop spending in that category until next month. “Cash stuffing” is simply the physical, viral-on-social-media version, where you literally stuff cash into labeled envelopes. And does it work? Yes, for many people it’s remarkably effective, because it turns abstract budget numbers into hard, visible limits you can’t easily ignore.
The method is old-fashioned, but its psychology is timeless: it’s much harder to overspend when you can physically see your grocery money running low than when you’re swiping a card with an invisible balance.
How it works
You start by budgeting your spending into categories, then allocate a set amount to each envelope at the start of the month. As you spend, you pull money from the relevant envelope. When the dining envelope is empty, you stop dining out until next month—no exceptions, no dipping into the grocery envelope. That hard stop is the entire point: the system removes the “I’ll just put it on the card and deal with it later” escape hatch that sinks so many budgets.
“Cash stuffing works because it makes money physical again. You can’t overspend an envelope that’s empty—the limit enforces itself.”
— A budgeting observation
Why it’s so effective
Several psychological forces make envelope budgeting powerful. Spending cash hurts more than swiping a card—research consistently shows people spend less when paying with physical money. The envelopes make your budget tangible and visual, so you feel your limits rather than just reading them. And the method enforces hard boundaries instead of soft intentions. For chronic overspenders or anyone who finds cards too frictionless, this concreteness can be a genuine breakthrough that other budgeting methods never deliver.
The drawbacks to weigh
It’s not perfect. Carrying and managing cash is inconvenient in an increasingly digital world, and many bills (rent, utilities, subscriptions) can’t be paid with cash in an envelope. There’s a security risk—lost or stolen cash is simply gone, with none of a card’s fraud protections. Cash also earns no interest when it sits in an envelope. And it doesn’t build credit the way responsible card use can. For these reasons, pure cash stuffing works best for discretionary, variable categories, while you handle fixed bills separately.
The digital version
You can capture the discipline of envelopes without the downsides by going digital. Many budgeting apps use a “digital envelope” or “zero-based” system that assigns every dollar to a category and tracks spending against it in real time—the same hard-limit psychology, with the convenience and security of cards and bank accounts. Some banks even let you create multiple sub-accounts that function like envelopes. This pairs naturally with learning to automate your finances, so your fixed bills and savings flow automatically while your envelopes govern discretionary spending.
A realistic example
Consider an illustrative case. Jamie consistently overspent on dining and impulse buys despite “having a budget.” She tried cash stuffing for her three problem categories—dining, entertainment, and shopping—putting $300, $100, and $150 in labeled envelopes each month, while keeping rent, utilities, and savings on autopay. The first month was eye-opening: watching the dining envelope thin out by mid-month made her cook at home far more. Within three months, her overspending had essentially stopped, and she’d redirected the savings into a goal. The physical limit succeeded where willpower alone had failed for years.
How it fits your broader budget
Envelope budgeting is a tactic, not a complete financial plan—it governs day-to-day discretionary spending, while the bigger picture needs structure too. It works beautifully alongside a lean bare-bones budget that defines your essentials, a sinking fund for irregular expenses, and a family budget everyone can follow. If your income varies, pair the envelope method with the buffer approach in our guide to budgeting on an irregular income. (This is general information, not personalized financial advice.)
Frequently Asked Questions
Does cash stuffing really work?
For many people, yes—especially chronic overspenders. Physically allocating cash into category envelopes creates hard, visible limits that curb overspending more effectively than abstract budget numbers or frictionless card swipes. The tangibility is what makes it click.
What’s the difference between envelope budgeting and cash stuffing?
They’re essentially the same method. Envelope budgeting” is the traditional term for dividing money into category envelopes; “cash stuffing” is the viral, literal version popularized on social media, where you physically fill labeled envelopes with cash.
What are the downsides of cash stuffing?
Managing cash is inconvenient, fixed bills can’t be paid from envelopes, lost or stolen cash has no fraud protection, the money earns no interest, and it doesn’t build credit. That’s why it’s best for discretionary categories, with bills handled separately.
Can I do envelope budgeting without cash?
Yes. Digital envelope or zero-based budgeting apps assign every dollar to a category and track spending in real time, giving you the same hard-limit discipline with the convenience and security of cards and bank accounts.
The Bottom Line
Envelope budgeting—and its viral form, cash stuffing—works because it makes spending tangible and enforces limits you can’t ignore. It’s especially powerful for discretionary categories and chronic overspenders, though cash’s inconveniences mean fixed bills belong elsewhere. Whether you use real envelopes or a digital version, the core idea is the same: give every dollar a job, and stop when the envelope’s empty.
Image Credit: Towfiqu barbhuiya; Pexels