Technology stocks fell another 1% during the latest session, but the headline decline hides a more important story. AI-related companies are no longer trading as one group. Investors are separating firms that can finance heavy spending from those that depend on debt and future profits.
I am Taylor Sohns, CEO of LifeGoal Wealth Advisors, a Certified Investment Management Analyst and Certified Financial Planner. From my perspective, investors need to know which type of AI company they own. A business with several profitable divisions faces a very different financial test than a pure-play AI provider.
Table of Contents
ToggleThe Market Is Looking Beneath the AI Label
For much of the AI investment cycle, companies connected to artificial intelligence often moved in the same direction. Strong demand, large spending plans, and high growth forecasts helped support many stocks.
That broad approach is starting to break apart. Investors are paying closer attention to balance sheets, financing needs, existing revenue, and the time it takes to generate profits.
The recent 1% drop in technology shares illustrates this shift. A sector-level decline does not explain which companies are under the most pressure. The larger differences appear inside the AI trade itself.
“Within the AI trade, there’s a massive separation between the haves and have-nots.”
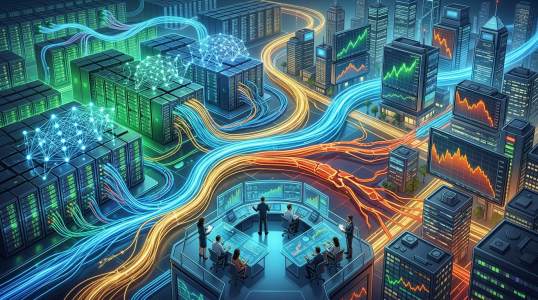
This separation can be viewed through two broad groups:
- Large hyperscalers with established businesses and several revenue sources
- AI-focused cloud providers that rely more heavily on outside financing
Both groups are spending heavily on data centers, chips, computing capacity, energy, and related infrastructure. However, they are not paying for that expansion in the same way.
View this post on Instagram
Hyperscalers Can Fund AI With Existing Businesses
The first group includes Meta, Microsoft, Amazon, and Google. These firms are often called hyperscalers because they operate enormous computing platforms and serve customers at global scale.
Their AI budgets are immense. They are investing in advanced chips, cloud capacity, data centers, software, and technical staff. That spending can place pressure on cash flow and raise questions about future returns.
Even so, these companies have an important advantage. They already own large businesses that generate revenue and cash. Those operations can help pay for AI investment while executives wait for new products to mature.
Microsoft has enterprise software and cloud services. Amazon has online retail, advertising, subscriptions, and cloud computing. Google has search advertising, YouTube, and cloud services. Meta has large advertising platforms tied to Facebook and Instagram.
AI can also support those existing operations. It may improve advertising systems, product recommendations, software tools, customer support, and cloud offerings. That creates multiple paths to financial returns.
Meta provides a useful example. Its AI spending does not need to produce revenue only through a separate AI product. Better recommendation systems can increase engagement. Improved advertising tools can help businesses reach likely customers. Those gains may support revenue inside an established business.
This does not make hyperscaler spending risk-free. Large projects can run over budget, and expected demand may take longer to appear. Competition can also force companies to keep spending before earlier investments earn an acceptable return.
Still, the hyperscalers have room to absorb mistakes. Their other business lines provide financial support, and their access to capital is generally stronger. That helps explain why the group’s shares were roughly flat over the prior year, despite concerns about the scale of AI spending.
Flat Performance Can Still Signal Relative Strength
A flat stock price may sound disappointing. In this case, it can indicate resilience.
Investors have questioned whether large technology companies are spending too much on AI. Yet their established revenue streams have helped prevent the same sharp declines seen among more concentrated providers.
The market appears willing to give these companies more time. Their current businesses can produce earnings while AI investments develop. They are not relying on one new market to cover every expense.
That distinction matters because AI infrastructure requires substantial spending before revenue arrives. Servers must be purchased. Data centers must be built or leased. Energy access must be secured. Customers then need time to adopt services and increase usage.
A company with healthy cash generation can carry those costs for longer. A company funded mainly through borrowing faces greater pressure if interest rates rise or investors become less willing to lend.
Pure-Play AI Providers Face a Financing Test
The second group includes NeoCloud companies such as CoreWeave, Oracle, and Iron, as discussed. These businesses offer investors more direct exposure to AI infrastructure and computing demand.
That focus can work well when capital is inexpensive, and growth expectations are rising. It becomes harder when financing costs rise, or markets question how quickly profits will arrive.
Unlike diversified hyperscalers, pure-play providers have fewer mature business lines available to fund expansion. They may need to borrow money, issue securities, or seek other forms of outside capital.
Debt creates a fixed obligation. Interest must be paid even if customer demand grows more slowly than expected. The company may also need new financing before its earlier projects generate enough cash.
Financing costs ballooned during the fall period discussed. As those costs rose, shares of more debt-dependent AI companies fell sharply.
“These are pure-play AI with no other revenue sources. They have to take on debt to finance.”
The issue is not simply whether AI demand exists. Investors are asking whether each company can remain financially stable long enough to benefit from that demand.
A provider could have valuable technology, strong customers, and rising sales, yet still face serious risk. Fast expansion can consume cash. Debt payments can grow. New capital may become expensive at the wrong time.
This creates a timing problem. AI profits may eventually become substantial, but creditors and operating expenses cannot always wait for that future.
Why Higher Financing Costs Change the Valuation
The cost of capital directly affects companies building expensive infrastructure. Higher interest costs reduce the amount of cash available for hiring, equipment, and expansion.
They also make future profits less valuable to investors. A dollar expected several years from now carries less weight when borrowing costs and required returns are higher.
This pressure is strongest for businesses that need repeated access to capital markets. One loan or funding round may not be enough. Data centers and computing equipment require continued investment, maintenance, and upgrades.
Investors should therefore look beyond revenue growth. Several questions deserve attention:
- Does the company generate enough cash to support its spending?
- How much debt does it carry, and when does that debt mature?
- Will it need additional financing before projects become profitable?
- Does it have other revenue sources if AI demand slows?
- Are major customers committed through durable contracts?
These questions help separate an attractive growth story from a financially sustainable business. A rising market can hide weak financing. A difficult market often exposes it.
This Is Not a Rejection of Artificial Intelligence
Sharp declines in AI-focused stocks may look like investors are abandoning the technology. I do not view the split that way.
The market is not necessarily losing faith in AI adoption. It is becoming more selective about who will earn the profits and who can survive the long investment period.
This is a key difference. Confidence in a technology does not require confidence in every company selling it.
The internet produced major economic change, but not every internet company succeeded. Cloud computing became central to modern business, yet results varied widely among providers. AI can follow a similar pattern.
Demand may grow while weaker companies struggle with debt, costs, or competition. Some firms may create useful services but fail to turn them into durable profits. Others may benefit because they own existing customers, distribution systems, and cash-producing operations.
“The market isn’t losing faith in AI. It’s losing faith that some of these companies will survive long enough to see the profits from it.”
What Investors Should Review in Their Portfolios
Owning an “AI stock” is not a complete investment strategy. The label says little about financial strength, valuation, debt, or revenue sources.
Iwould start by identifying the role each holding plays. Is it a diversified technology company using AI to improve existing products? Is it a cloud provider selling computing capacity? Is it an infrastructure business that must borrow heavily to expand?
Next, review how the company pays for growth. Cash from operations is different from borrowed money. Both can fund expansion, but debt adds deadlines and interest expense.
Investors should also consider concentration. A company tied almost entirely to AI infrastructure may offer greater upside if demand exceeds forecasts. It may also suffer more if construction costs rise, customers delay orders, or financing becomes scarce.
Price movement alone does not provide the full answer. A falling stock is not automatically cheap, and a stable stock is not automatically safe. The business model and balance sheet remain central.
The current split among AI companies offers a practical lesson. Themes can attract attention, but cash flow determines how long a company can pursue its plans. Investors should understand both before committing capital.
AI remains a major investment trend, yet the likely winners will not be chosen by the label alone. Financial endurance, existing revenue, and access to affordable capital may decide which firms reach sustained profitability.
My recommendation is simple: know which camp your holding belongs to. Study how it funds growth, how long it can support heavy spending, and whether current operations provide a margin for error.
Frequently Asked Questions
Q: What is the difference between a hyperscaler and a pure-play AI provider?
A hyperscaler operates very large computing platforms and usually has several established businesses. A pure-play provider depends more directly on AI-related demand and may have fewer revenue sources.
Q: Does weakness in AI stocks mean the AI investment cycle is ending?
Not necessarily. The price split may show that investors are judging companies by financial strength, debt, and expected profitability rather than treating every AI business alike.
Q: What financial measures should AI investors examine?
Investors should review operating cash flow, total debt, interest expense, debt maturity dates, capital spending, customer concentration, and the likely need for future financing.
Image Credit: Pexels