A comfortable retirement depends on more than reaching one large savings number. Measure progress throughout a career. I use age-based savings targets to help people check whether their retirement plans are generally on track. These simple benchmarks connect savings to salary, making them useful across many income levels.
I am Taylor Sohns, CEO of LifeGoal Wealth Advisors, a Certified Investment Management Analyst and Certified Financial Planner. As a financial advisor managing more than $500 million, I have seen how clear targets can make retirement planning easier. The central goal is to save enough to replace about 80% of pre-retirement income, including Social Security benefits.
Table of Contents
ToggleThe Retirement Savings Targets by Age
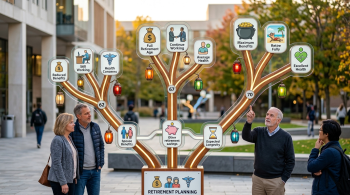
A practical rule of thumb compares retirement savings with current annual salary. The target rises as a person moves through the highest-earning years of a career.
- By age 30, aim to save about one times your annual salary.
- By age 40, aim to save about three times your annual salary.
- By age 50, aim to save about six times your annual salary.
- By age 60, aim to save about eight times your annual salary.
- By retirement age, aim to save about 10 times your annual salary.
For example, someone earning $75,000 at age 30 would have a target of about $75,000. At age 40, the target would rise to roughly $225,000 if that salary stayed the same.
A 50-year-old earning $100,000 would aim for approximately $600,000. By retirement, a worker earning $100,000 would generally target about $1 million.
These figures are checkpoints, not rigid deadlines. Salary changes, retirement timing, investment results, pensions, and personal spending needs can all affect an appropriate target.
View this post on Instagram
Why Retirement Targets Use Salary
Retirement needs are closely tied to lifestyle. A person earning $50,000 may have different spending habits than someone earning $200,000. Connecting savings goals to salary adjusts the benchmark to the worker’s likely standard of living.
This approach is also easier than trying to predict every expense decades ahead. Few 30-year-olds know what health care, housing, or travel will cost in retirement. A salary multiple offers a simple progress check without requiring perfect forecasts.
The benchmark also grows over time. Early in a career, retirement balances may seem small. Later, higher contributions and years of investment growth can have a greater effect.
At age 30, aim for roughly one times your salary. By retirement age, the target rises to about 10 times your salary.
The gradual increase matters. Retirement readiness is usually built through steady saving, not one large contribution near the end of a career.
How the 80% Income Goal Works
The savings targets are designed to support retirement income near 80% of pre-retirement earnings. A person earning $100,000 before leaving work might therefore plan for about $80,000 in annual retirement income.
Retirees often need less than their full working income. Payroll taxes may decline, retirement contributions stop, and commuting costs can disappear. A mortgage may also be paid off.
However, expenses do not fall for everyone. Some households spend more on travel, hobbies, or family support during the first years of retirement. Medical and long-term care costs may rise later.
That is why 80% should be treated as a starting point. Someone with modest expenses may need less. A household planning an active retirement may need as much as its previous income, or more.
Social Security Covers Part of the Need
Personal savings do not have to provide every dollar of retirement income. Social Security covers roughly 40% of pre-retirement income for the average American.
Suppose a worker earned $80,000 before retirement and wanted to replace 80%, or $64,000 per year. If Social Security supplied income equal to about 40% of prior earnings, it could provide around $32,000. Savings and other income sources would need to supply the remaining amount.
This example is simplified. Actual benefits depend on earnings history and the age at which benefits begin. Married couples may also have different claiming choices than single retirees.
Higher earners should be careful with the 40% estimate. Social Security replaces a larger share of earnings for lower-income workers. It often replaces a smaller share for people with high salaries.
A pension, rental property, part-time work, or an annuity may also help close the gap. Each reliable income source can reduce what must come from an investment portfolio.
Why a Margin for Error Matters
Retirement plans cover many years and must account for events that cannot be predicted with precision. Market declines, inflation, taxes, medical bills, and a longer life can place pressure on savings.
A person who retires at 65 may need income for 25 or 30 years. Some retirees will need it for even longer. Saving close to 10 times salary can provide room for unexpected costs and periods of weaker investment returns.
A margin for error can also protect spending choices. Without enough savings, retirees may have to cut back on travel, move to a less expensive home, or depend more heavily on family.
The goal is not to build the largest possible account at the expense of every current priority. It is to create a reasonable balance between present needs and future security.
What to Do if You Are Behind
Missing an age-based target does not mean retirement is out of reach. It means the plan deserves attention. You can often reduce the gap through several practical changes.
- Increase the contribution rate, even if the first increase is small.
- Capture the full employer match when available.
- Direct part of each raise or bonus into long-term savings.
- Review investment costs, taxes, and portfolio risk.
- Consider retiring later or delaying Social Security benefits.
- Build a retirement budget based on expected spending.
Small increases can add up over time. Raising contributions by one percentage point each year may feel more manageable than making one large adjustment.
Workers age 50 and older may also qualify for catch-up contributions in certain retirement accounts. Contribution limits can change, so review current rules before acting.
Retirement timing is another useful planning tool. Working for an extra year can add contributions, allow investments more time to grow, and shorten the period funded by savings.
What to Do if You Are Ahead
Exceeding a benchmark is positive, but it does not remove the need for planning. A large account can still face excessive risk, high fees, poor tax decisions, or an unrealistic spending plan.
Savers who are ahead may have more flexibility. They might retire earlier, spend more, support relatives, give to charity, or leave assets to heirs.
Test those choices against future income and expenses. A savings balance alone doesn’t show how much you can safely spend each year.
Use the Benchmarks as a Starting Point
These salary multiples provide a quick check, not a personal financial plan. Two workers of the same age and salary may need very different savings balances.
One may have a pension and a paid-off home. The other may rent, support family members, and plan to retire early. Their needs will not be identical.
Investment mix also matters. Cash, bonds, and stocks have different levels of risk and expected growth. A retirement account should match the saver’s timeline, financial capacity, and comfort with market losses.
I recommend reviewing progress at least once a year. Update salary, savings balances, contribution rates, expected Social Security benefits, and the planned retirement date. Major life changes may require an earlier review.
The central lesson is simple. Aim for one times salary by 30, three times by 40, six times by 50, eight times by 60, and about 10 times by retirement. Those checkpoints can support an income near 80% of pre-retirement earnings when combined with Social Security. Use them to measure progress, identify gaps, and make adjustments while time remains on your side.
Frequently Asked Questions
Q: Do retirement savings targets include workplace accounts?
Yes. The total generally includes retirement assets such as 401(k), 403(b), traditional IRA, and Roth IRA balances. Other investments intended for retirement may also count. Emergency savings should usually remain separate.
Q: What if my salary recently increased?
A major raise can make the target appear farther away overnight. That does not mean the plan suddenly failed. Review the new income, expected lifestyle, contribution rate, and years until retirement before setting an updated goal.
Q: Is saving 10 times salary enough for everyone?
No single multiple fits every household. Ten times salary is a useful general target. Early retirement, high spending, limited Social Security benefits, or major health costs may require more. A pension or lower spending may reduce the amount needed.
Image Credits: