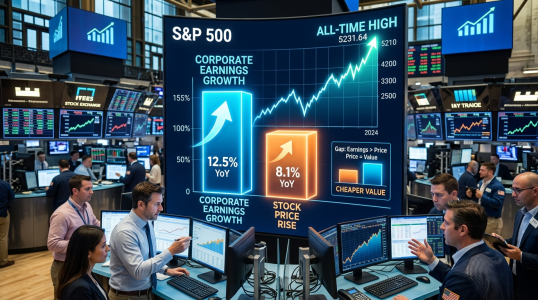
The S&P 500 recently closed at an all-time high, but that record doesn’t tell the full story. Analysts expect corporate earnings to grow much faster than stock prices. That gap may leave stocks cheaper on an earnings basis than they were a year ago.
I am Taylor Sohns, CEO of LifeGoal Wealth Advisors, a Certified Investment Management Analyst and Certified Financial Planner. I manage more than $500 million and use market data to look past simple headlines. Record prices can sound alarming, but price alone is not the same as value.
Table of Contents
ToggleRecord Prices Do Not Automatically Mean Expensive Stocks
Investors often judge the market by its index level. If the S&P 500 reaches a record, many assume stocks must be unusually expensive. That conclusion can miss the role of corporate profits.
A stock represents ownership in a business. Its value is tied partly to the profits that business earns, or may earn in the future. If profits rise faster than the share price, the stock can become less expensive relative to those profits.
This is the key distinction between price and valuation. Price shows what investors must pay for a share. Valuation compares that price with earnings, sales, cash flow, or another business measure.
“Although the S&P is at all-time highs, stocks have not gone up 30% in the past year to match the earnings growth.”
That comparison helps explain why a market can set a record while becoming cheaper on an earnings basis. The index may be higher in dollar terms, yet each dollar invested may purchase a larger share of expected profits.
View this post on Instagram
Earnings Expectations Are Far Above the Average
Wall Street analysts expect S&P 500 companies’ earnings to grow about 30% from the prior year. That estimate stands far above the index’s reported 10-year average earnings growth rate of roughly 9%.
The technology sector is expected to grow even more. Analysts project about 65% earnings growth for the sector compared with the previous year.
These figures create a sharp contrast:
- The S&P 500 recently reached an all-time closing high.
- Analysts expect about 30% year-over-year earnings growth for the index.
- The 10-year average earnings growth rate is about 9%.
- Technology earnings are expected to grow about 65%.
- Stock prices have not risen enough to fully match the projected earnings gains.
If those forecasts prove accurate, the market’s earnings will have increased faster than its price. That would reduce the amount investors pay for each dollar of earnings, assuming other factors remain equal.
The phrase cheaper than last year does not mean share prices are lower. It means the price-to-earnings relationship may be more attractive. That is a relative valuation statement, not a claim that stocks are objectively cheap under every measure.
How the Price-to-Earnings Ratio Explains the Difference
The price-to-earnings ratio, often called the P/E ratio, is one common valuation measure. It divides a stock’s price by its earnings per share. The same idea applies to a broad index.
Consider a simple example. Suppose an index is priced at 100 and earns 5. Its P/E ratio is 20 because investors pay 20 times earnings.
Now suppose earnings rise 30% to 6.50, while the index price increases only 10% to 110. The new P/E ratio falls to about 16.9. The index costs more than before, but it is cheaper relative to earnings.
This basic math is behind the current argument. If S&P 500 earnings grow near the expected rate, and index prices lag that growth, the valuation multiple declines.
Investors can easily overlook this effect because index records receive more attention than earnings growth. A headline about an all-time high is simple. Comparing prices with changing profits requires another step.
Why Earnings Season Matters
Earnings season lets investors test these forecasts against actual company results. Companies report revenue, expenses, profits, and guidance about coming quarters.
The results matter because the 30% and 65% figures are analyst expectations. They are not guaranteed outcomes. A valuation that looks attractive based on projected earnings may look different if those profits don’t materialize.
During earnings season, I would watch several areas:
- Whether reported earnings meet or exceed analyst estimates.
- Whether revenue growth supports the profit increase.
- How much growth comes from lasting demand rather than temporary cost cuts.
- Whether company leaders raise or lower future guidance.
- Whether technology growth is concentrated in a small number of large firms.
Strong reported profits could support current index levels. Weak results could lead investors to question whether prices already reflect too much optimism.
Market reactions may also depend on expectations rather than the reported number alone. A company can deliver strong growth and still see its shares decline if investors expected even better results.
Technology Has an Outsized Role
The projected 65% earnings growth for technology is striking. It also deserves careful interpretation because large technology companies carry heavy weights in the S&P 500.
A small group of very large companies can strongly affect the index’s total earnings and price. Strong technology profits may lift overall numbers even if results are less impressive elsewhere.
This doesn’t make the earnings growth any less meaningful. It does mean investors should examine where the gains come from. Broad profit growth across many industries may signal something different than growth concentrated in a few companies.
Sector results can also vary widely. Financial firms respond to interest rates and credit conditions. Energy profits depend heavily on commodity prices. Consumer companies face changes in household spending and labor costs.
For that reason, a single index-level figure cannot describe every company. Some stocks may be attractively valued, while others may already price in years of strong growth.
What the “Cheaper” Claim Does and Does Not Mean
The central claim is narrow but useful. Stocks may be cheaper relative to earnings than they were at the same time last year. That does not mean the market cannot fall, nor does it promise positive returns.
Valuation is only one part of market analysis. Interest rates, inflation, economic growth, profit margins, investor sentiment, and geopolitical events can all affect stock prices.
Interest rates are especially relevant. Investors often accept higher stock valuations when bond yields are low because alternatives offer less income. Higher yields can put pressure on stock multiples, even if earnings remain healthy.
Forecast risk also matters. Analysts revise estimates as new information arrives. A projected earnings surge can shrink if sales weaken, costs rise, or management teams issue cautious guidance.
Investors should therefore avoid turning one encouraging data point into a broad market prediction. The earnings outlook offers context for record prices, but it cannot remove uncertainty.
A Better Way to Read Market Headlines
Record highs often trigger emotional reactions. Some investors fear they have missed their chance to buy. Others expect an immediate decline because the market appears too elevated.
Neither response starts with enough information. Markets frequently reach records during long periods of economic and profit growth. A record simply means the index is higher than it has been before.
A more useful review asks several questions:
- How quickly are corporate earnings growing?
- Have prices risen faster or slower than those earnings?
- Are forecasts improving or weakening?
- Which sectors and companies are producing the growth?
- How do current valuations compare with history and interest rates?
This approach replaces a dramatic headline with measurable facts. It also helps investors separate market level from market value.
Long-term investment decisions should still fit personal goals, time horizons, and risk limits. A strong earnings season does not make every stock suitable for every portfolio.
The recent S&P 500 record deserves attention, but it shouldn’t be viewed in isolation. Expected earnings growth of 30%, including 65% growth in technology, changes the valuation discussion. Those estimates are far above the reported 10-year average of 9%.
If profits rise as forecast and prices continue to trail that growth, stocks may remain cheaper relative to earnings than they were last year. Earnings season will show how much of that optimism is supported by actual results.
My recommendation is simple: look past the index level. Compare price growth with profit growth, examine the source of those profits, and keep forecasts in perspective. The clearest market view often sits behind the headline.