Many investors treat an S&P 500 fund as a simple way to spread risk across 500 companies. That description is technically correct, but it can hide how much a few companies influence results. I believe investors should look inside the index before deciding how diversified their portfolios truly are.
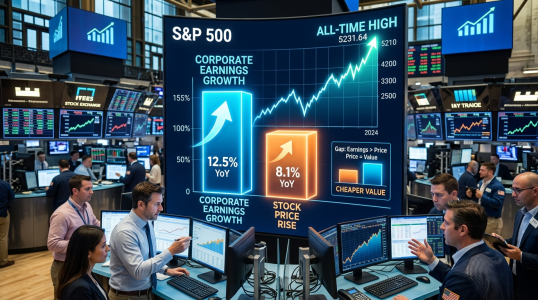
Current earnings estimates show why this matters. Two companies are expected to add more earnings growth than the bottom 490 S&P 500 companies combined. That level of concentration can shape index returns, market expectations, and portfolio risk.
Table of Contents
ToggleOwning 500 Companies Does Not Mean Equal Exposure
The S&P 500 is market-cap weighted. Larger companies receive larger positions, while smaller members receive less influence. Investors do not own an equal amount of every business through a standard index-tracking fund.
A company’s weight rises as its market value grows. If a small group of stocks climbs much faster than the rest, those companies can account for a growing share of the index.
This structure has practical consequences. A fund may hold hundreds of stocks, yet much of its daily movement can depend on a handful of very large businesses.
“Index investing may give you 500 companies of exposure, but pop the hood and two matter more than the other 490 combined.”
The comparison refers to expected earnings growth, not the total earnings generated by every company. That distinction matters. The claim does not mean only two businesses are profitable or relevant. It means analysts expect an unusually large share of added profit growth to come from just two companies.
Investors should also note that the bottom 490 companies are not necessarily poor businesses. Some may be growing slowly, while others could face temporary earnings declines. Their combined contribution may still look modest beside the rapid growth expected from the largest technology and semiconductor names.
View this post on Instagram
Three Forms of Concentration Investors Should Review
Portfolio concentration can take several forms. Counting holdings addresses only one of them.
- Weight concentration: A small number of companies may represent a large share of the index’s value.
- Earnings concentration: A few businesses may produce most of the expected profit growth.
- Industry concentration: Several major holdings may depend on similar trends, customers, or spending cycles.
These risks can overlap. Several large technology companies may benefit from the same rise in artificial intelligence spending. They may also rely on related data center budgets, chip production, cloud services, or enterprise investment.
That shared exposure can help returns during periods of strong demand. It can also create pressure if spending slows, profit margins narrow, or analysts reduce their forecasts.
A long list of company names doesn’t measure diversification. Investors should ask how much capital sits in the largest positions and what economic forces drive those holdings.
Micron Shows Why Strong Earnings May Not Lift a Stock
Micron provides a useful example of the gap between business results and stock performance. The company reported that earnings per share surged about 1,000%, yet its stock traded lower after the report.
That reaction may seem confusing. If earnings rose so sharply, why would the stock fall?
Markets usually focus on expectations rather than a single reported number. A company can deliver strong growth and still disappoint investors if its results, outlook, or management comments fall short of what the market had already priced in.
A 1,000% increase can also reflect a weak starting point. Earnings growth percentages look especially large when the prior period had very low profits. The percentage remains accurate, but it may not tell the full story.
Investors may also focus on future demand, production costs, pricing, inventory, and profit margins. Semiconductor businesses often move through cycles. Strong current results do not remove concerns about the next phase of that cycle.
Micron’s reaction offers a clear lesson: good news does not guarantee a positive stock return. The key question is whether the news is better or worse than investors expected.
Nvidia Faces a High Bar
Nvidia was expected to report about 90% earnings growth. That forecast reflects strong demand, but it also sets a high bar.
A company growing earnings at that pace can justify close attention. Yet rapid growth alone does not determine what happens next. The stock’s valuation, expected results, future guidance, and investor positioning all matter.
If investors already expect exceptional performance, merely meeting estimates may not be enough to lift the stock. The market may want higher revenue, wider margins, or a stronger outlook. Even a strong report can produce a muted or negative response.
This is why I separate company quality from investment outcome. A business may have strong products and rising profits, while its stock still falls over a short period. Price reflects both financial results and prior expectations.
Nvidia also carries unusual influence because of its size and its role in artificial intelligence infrastructure. Its earnings can affect technology stocks, semiconductor companies, and broad index funds at the same time.
For an investor holding an S&P 500 fund, that influence may be indirect but meaningful. A large move in Nvidia can affect the entire index, even though the fund owns hundreds of other companies.
What Concentration Means for Index Investors
None of this makes index investing inherently flawed. Broad, low-cost index funds remain useful tools for many long-term investors. They can reduce the risks tied to selecting one company, and they often charge lower fees than active strategies.
The concern is not index ownership itself. The concern is assuming one index provides all the diversification an investor needs.
An S&P 500 fund mainly holds large American companies. It may offer limited exposure to smaller firms, foreign markets, bonds, and other assets. It can also become more concentrated as its largest members rise in value.
Investors can review several questions before calling a portfolio diversified:
- How much of the portfolio is held in its five or ten largest companies?
- Do the biggest holdings depend on the same economic or technology trends?
- Is the portfolio spread across company sizes, regions, and asset types?
- Would one disappointing earnings report have an outsized effect?
- Does the current risk match the investor’s time horizon and financial goals?
The right answers will differ by investor. Someone with decades before retirement may accept more stock exposure and short-term volatility. A retiree who needs regular withdrawals may value stability and income more.
Therefore, judge diversification at the total portfolio level. An investor might hold an S&P 500 fund alongside international stocks, smaller companies, and high-quality bonds. The mix should reflect personal goals rather than a popular market label.
A Better Way to Read Earnings Headlines
Large percentage figures attract attention, but they require context. Look past the headline before drawing a conclusion about a company or the index.
Start with the comparison period. A sharp rebound from a weak year can produce an impressive growth rate. Then compare the actual result with analyst forecasts. Markets tend to respond to the difference.
Next, review management’s forecast for future quarters. A company can beat past estimates while warning that demand may slow. Investors often weigh that outlook more heavily than the completed quarter.
Finally, consider valuation. Strong growth may already be reflected in the stock price. Higher valuations can leave less room for disappointment, especially when expectations are elevated.
These steps apply to Micron, Nvidia, and other major index members. They also help investors avoid treating a single earnings percentage as the whole investment case.
Diversification Requires More Than a Label
The central lesson is straightforward. Owning many securities can reduce some risks, but the number of holdings doesn’t show how evenly those risks are spread.
Two companies adding more expected earnings growth than the bottom 490 combined is a striking signal. It shows how dependent broad market expectations can become on a very small group of businesses.
That dependence may support strong index returns while growth continues. It can also increase sensitivity to earnings misses, weaker forecasts, regulatory changes, or shifts in technology spending.
Investors do not need to abandon index funds because of this concentration. They should know what they own, review the largest weights, and avoid confusing a high company count with balanced exposure.
As CEO of LifeGoal Wealth Advisors and a Certified Investment Management Analyst and Certified Financial Planner, I view that review as part of informed portfolio planning. The goal is not to predict every earnings reaction. The goal is to build a mix that remains suitable when market leadership changes.
A broad index can still play an important role. Yet diversification should be measured by weight, earnings exposure, industry drivers, and the investor’s full financial plan. Before relying on the number 500, look beneath the label.
Frequently Asked Questions
Q: Is the S&P 500 still considered diversified?
Yes, it owns shares in hundreds of companies across several industries. However, its largest members have much more influence than the smallest. Investors should assess both the number of holdings and their weights.
Q: Why can a stock fall after reporting major earnings growth?
A stock may decline if results fail to exceed high expectations or if management gives a weaker outlook. Large growth percentages may also come from an unusually low prior-year result.
Q: How can investors reduce reliance on a few large companies?
They can review funds with different weighting methods and consider exposure to smaller companies, international markets, or bonds. Any change should fit the investor’s goals, time horizon, and ability to accept losses.
Image Credit: Ivan Babydo; Pexels