Table of Contents
ToggleKey Takeaways
- Unlike stock market gains (7% to 10%), high-interest debt (like credit cards with 20%+ APR) compounds against you quickly. You can’t out-invest high-interest debt.
- When you pay off a loan or credit card, immediately redirect the exact monthly payment into a tax-advantaged retirement vehicle (like a 401(k), IRA, or Solo 401(k)).
- Thoroughly vet third-party providers before deciding whether to consolidate your debt, settle it, or send collection notices. Before paying collectors, make sure new consolidation rates are lower, watch out for 15–20% settlement fees, and request debt validation.
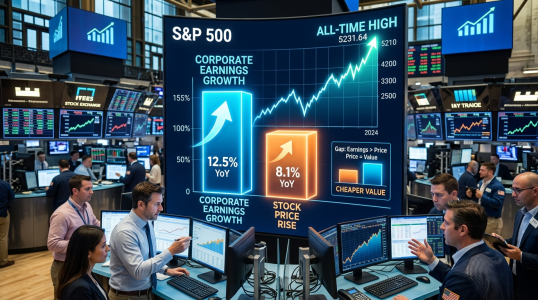
When entrepreneurs and professionals talk about retirement readiness, the topic almost always turns to stocks. We check S&P 500 returns, stress over index fund allocations, and obsess over volatility.
However, a National Institute on Retirement Security (NIRS) survey indicates that market fluctuations aren’t the primary factor hindering millions of Americans from retiring comfortably.
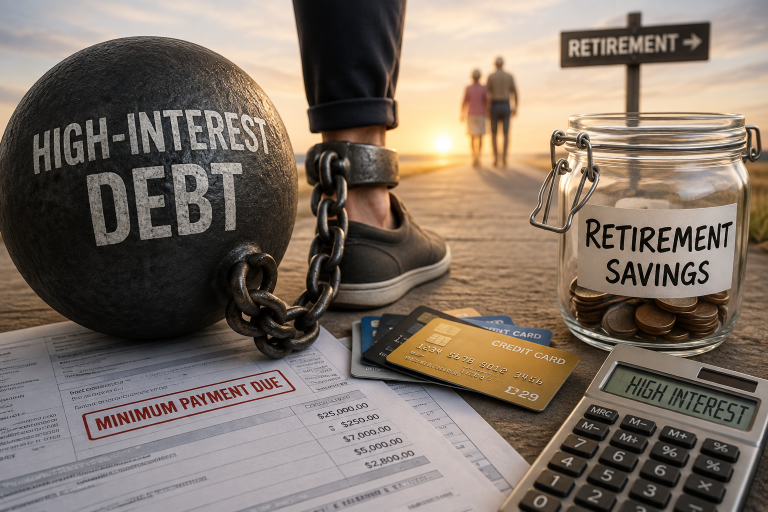
The real culprit? Debt. In fact, almost three-quarters of Americans say their debt is a problem, while 77% say it keeps them from saving for retirement.
Although stock market gains have reached record levels, personal balance sheets reveal a very different story. High-interest credit card debt, persistent personal loans, auto debt, and long-term mortgages carried into later life drain disposable income before it reaches an investment account. High interest rates compound this drag, silently eating away capital that should be building wealth for the future.
As such, founders, entrepreneurs, and professionals alike should take note: You can’t out-invest a debt problem.
Here’s why high-interest liabilities are eroding your cash flow-and a practical, step-by-step plan to eliminate them.
The Hidden Cost of Debt on Retirement Savings
If you consider compounded returns, you can see why debt is the main bottleneck to retirement security:
- Stock market returns. Historically, diversified equity portfolios have produced annual returns of 7% to 10% before inflation.
- The highest-interest debt rate. The average credit card interest rate hovers around 20% APR. Most personal loans and high-interest lines of credit charge 10% to 15% interest.
When you carry consumer debt while investing, you’re trying to climb down a downward slope. If you pay 22% annual interest on a credit card balance, you’ll never make realistic gains in a 401(k), IRA, or taxable brokerage account. In the long run, every dollar spent on interest on debt loses its compounding power.
In addition, debt restricts cash flow liquidity. When you rely heavily on debt service payments to pay the bills, you lose the flexibility to contribute to tax-advantaged accounts or take advantage of market dips.
Step 1: Audit and Categorize Your Debt Load
To eliminate debt, you need to see everything you owe. People avoid facing their total debt because it creates psychological friction, but clarity is necessary to act.
List every non-mortgage liability on your balance sheet:
| Debt Name | Principal Balance | Interest Rate (APR) | Minimum Monthly Payment |
| Credit Card A | $12,500 | 23.4% | $350 |
| Personal Loan | $8,000 | 11.2% | $220 |
| Auto Loan | $18,000 | 6.5% | $410 |
Categorize your debt into toxic debt (anything with an interest rate higher than 7-8%) and manageable debt (fixed, low-interest loans, such as a low-rate mortgage). The goal should be to eliminate toxic debt as soon as possible.
Step 2: Choose Your Payoff Strategy—Avalanche vs. Snowball
You can systematically eliminate liabilities by implementing one of two proven financial frameworks:
Option A: The Debt Avalanche Method (Mathematically Superior).
- How it works. Sort your debts by interest rate, highest to lowest. Pay the minimum on all accounts and put every extra dollar toward the balance with the highest APR.
- Why it works. By minimizing the total interest paid over time, cash flow is freed up faster.
Option B: The Debt Snowball Method (Behaviorally Superior)
- How it works. Sort your debts descendingly by balance size, regardless of interest rate. Whenever you have extra funds, use them to pay off the smallest balance first.
- Why it works. It builds momentum and habits needed for long-term consistency by creating quick psychological wins.
Choose the Avalanche if you are disciplined and data-driven. The Snowball is a good choice if you need psychological motivation to stick with your plan. Ultimately, you should choose the method you are most likely to implement.
Step 3: Lower Your Weighted Average Interest Rate
Wouldn’t it be better to pay 0% to 10% interest instead of 22 percent? As a result of restructuring, your monthly carrying costs will be lower, allowing a greater portion of your payments to be applied to principal reduction each month.
- Leverage 0% APR balance transfer cards. If your credit score is strong, transfer your high-interest credit card balances to a 0% introductory APR card (often lasting 12 to 21 months). But create a structured plan to pay off the balance before the promotional period ends.
- Negotiate directly with lenders. Contact your credit card issuer and ask for a rate reduction. Provide proof of a strong payment history or lower rates elsewhere. Proactive cardholders often see lenders reduce APRs by 3% to 7%.
- Consider personal consolidation loans. Consolidate multiple high-interest credit cards into a single fixed-rate personal loan to lower your interest rate.
Step 4: Pivot Freed-Up Cash Flow Directly to Retirement Accounts
Many financial advisors miss the pivotal step when giving financial advice. People often allow that freed-up cash flow to dissolve into lifestyle creep once they pay off a debt.
Instead, automate the transfer of every freed-up dollar directly into retirement vehicles.
The retirement stacking hierarchy.
- Capture the full employer match. Even while paying down debt, if you have access to a traditional 401(k) with a company match, contribute enough to get 100% of the match. You get an immediate 100% return on your investment.
- Max out your Health Savings Account (HSA). An HSA offers a rare triple tax advantage (tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses).
- Fund a Roth IRA or Traditional IRA. Contribute to an IRA annually to take advantage of tax-free growth or upfront tax deductions.
- Utilize entrepreneur-specific accounts. If you are self-employed, consider SEP-IRAs or Solo 401(k)s, which allow higher annual contribution limits than standard individual accounts.
Step 5: Use Caution When Navigating Debt Relief and Recovery Options
If a company offers to assist with debt management, be extremely cautious. Check the legitimacy of the company and its offers, and choose the option that best fits your needs:
- Debt consolidation. By consolidating debts, you can reduce monthly payments while streamlining your loans. It requires the borrower to pay off all their debt balances using new loans. This approach works best if you can get a loan at a lower interest rate; otherwise, you’re just moving debt around.
- Debt settlement. A debt settlement company negotiates a lump-sum payment with your creditors instead of you paying the entire amount owed. Typically, these companies charge 15 to 20 percent of the total debt as a fee.
- Debt collection. Always verify a debt’s validity before paying anything to a debt collection company. Dispute the debt collector’s claim if you think it’s incorrect.
Consumers in California, for example, have specific rights under the Rosenthal Fair Debt Collection Practices Act (RFDCPA). Unlike federal protections, California law prohibits both third-party collectors and original creditors from using deceptive and harassing tactics and gives consumers explicit rights to dispute debts and request verification.
The Path Forward: Reclaiming Your Future
Historically, the stock market has been one of the most powerful wealth-building engines. The problem is that trying to maximize market returns while burdened by high-interest consumer debt is like racing with the parking brake on.
With a focused payoff strategy, lower carrying costs, vetted debt-relief providers, and immediate redirection of freed-up cash flow into tax-advantaged retirement accounts, your financial baseline shifts from defensive debt servicing to offensive compounding.
Start controlling your balance sheet today, because your ultimate goal as an entrepreneur is not only revenue generation, but long-term security.
Image Credit: Albert Costill/ChatGPT