True wealth can’t be built by following outdated playbooks handed down from your parents or learned in traditional school. For real financial freedom, you need unconventional strategies — wealth hacks that actually work.
On one of my regular wealth walks, I reflected deeply on my financial journey. I started asking myself: What specific investments took me from broke to millionaire?
When I sat down and really analyzed the numbers, it came down to two things.
The first investment is one you’ll hear about from almost every financial expert and self-made millionaire. The second, however, is completely different. Although it is rarely discussed in mainstream finance, it has completely transformed my life.
Investment #1: The Stock Market (But Not the Way You Think)
Stocks are the ultimate wealth-building engine, so their inclusion here is no surprise. However, you need to know where my journey actually began to understand why it had such an impact on me.
I didn’t inherit a fortune or grow up with a silver spoon in my mouth. Financially, my parents were broke. Although they did their best, they couldn’t pass down the financial blueprint that built a fortune. In fact, both my parents filed for bankruptcy twice.
Without a head start, I began my wealth journey at basically zero. After college, I earned a finance degree and began studying how money works.
In the early days of investing, I had little money to my name. My first move was to contribute $25 a month to a subpar mutual fund. That was the whole strategy. I started with a tiny, automated monthly draft from my checking account into a Roth IRA, not thousands of dollars.
By taking small, consistent actions, I gained early market exposure and let compounding do its magic. Over time, that consistency paid off greatly.
What I did differently: Breaking the index fund rule.
Here’s where my investment philosophy differs from that of modern financial gurus.
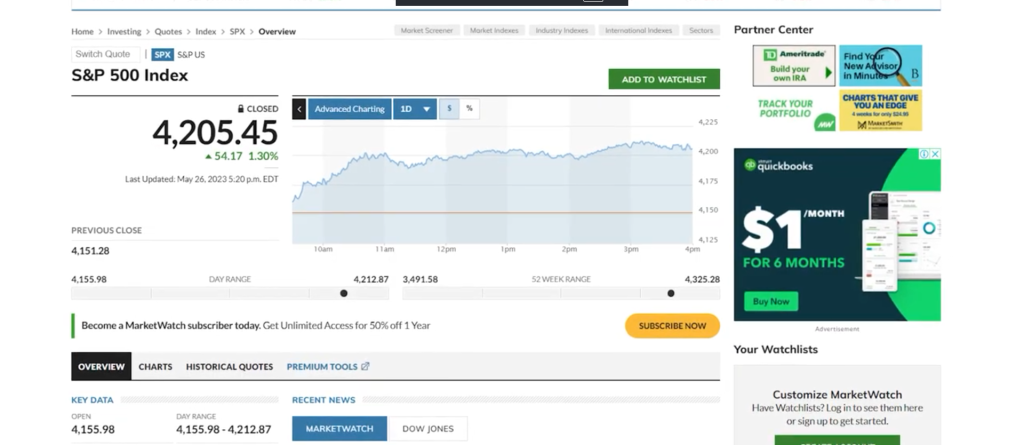
Experts say to put 90% of your money into an S&P 500 index fund and leave it alone, according to most investing blogs. Honestly, I’ve never purchased an S&P 500 index fund.
Back then, my logic was simple. Typically, a company isn’t added to the S&P 500 until it has already achieved a massive valuation. I reasoned that it made more sense to invest in these companies before they became large enough to be included in the index.
I wasn’t looking into a crystal ball. Based on my own research, I invested heavily in companies whose products I understood, trusted, and used.
Under Armor, for instance, was one of my first stock purchases. When they launched their IPO, I was deployed to Iraq. Since it was 130 degrees outside, I wore their gear daily to stay cool. Having experienced the product’s value firsthand, I bought the stock multiple times, rode the wave up, and locked in massive gains.
Later, I used the same philosophy to invest in growth companies like Visa and Facebook. Every dollar of growth was tax-free because these assets were held in a Roth IRA.
Why this high-risk strategy worked for me.
Because my business ran parallel to my portfolio, I was comfortable taking on individual stock risks.
In addition to generating revenue, my business also served as my primary source of financial security. I could be much more aggressive with my retirement account because my living expenses and income were covered. Even though this risk tolerance may not suit everyone, it was perfect for me.
Today, my strategy focuses on cash flow. While I still have some growth stocks like Tesla, I’m diversifying into dividend-paying stocks, specifically long-standing Dividend Aristocrats and Dividend Kings.
The beauty of modern investing is that entry barriers have completely disappeared. With fractional shares, you can get real-world experience and make mistakes with little risk when you’re just starting out.
Investment #2: My Personal and Online Brand
Among my net worth assets, the single asset that had the greatest impact was not a stock or a traditional fund. It was a deliberate, consistent investment in my personal brand.
Your reputation, your authority, and your online presence are your most valuable assets. Looking back, treating my name like a business altered my entire financial trajectory.
As a first step, I invested the time and money necessary to earn the Certified Financial Planner designation. You don’t need to be a CFP to work in financial services. The exam is brutal and requires months of grueling study. Passing didn’t automatically result in a pay raise, but it gave me instant legitimacy. Those credentials helped me stand out from the competition and prove to clients that I was a serious advisor.
From there, I continuously invested my revenue back into my brand’s infrastructure. I bought a premium website, high-end business cards, and professional camera and lighting equipment. My marketability rose with every upgrade. Back then, very few financial planners blogged or recorded videos. By treating content creation like a professional business, I got a huge head start.
As I honed my writing skills and built relationships, I eventually landed regular columns on major platforms like Forbes, Business Insider, and CNBC.
Does this massive media outlet send you a big check for your articles? In most cases, no. However, the real ROI isn’t in the freelance fee. It’s the permanent stamp of authority that makes it valuable. Once a prospective client or viewer sees you’ve been featured in top-tier financial publications, their perception of you changes.
The hard truth about measuring your return.
Because you cannot easily quantify the return on investment of a personal brand, most people do not make this second investment.
If you buy a stock, you can see a clear percentage gain when you log into your account. But when you spend money on a website designer, a camera, a certification, or networking, there’s no dashboard to show your profit. It can feel like a sunk cost or a waste of money.
Because people cannot see a math equation instantly, they play it safe. People keep doing the same old thing that doesn’t work, so they wonder why their income stagnates.
What Are You Going to Invest In?
One of the best things about these wealth accelerators is that anyone can use them. You don’t need a huge inheritance or special permission. In minutes, you can open a brokerage account and start building your own platform and authority.
Whether you focus on building your brand equity, investing in individual markets, or leveraging both at the same time, the choice is entirely up to you.
What will you do today to start investing in your financial freedom? If you want to build a massive net worth and end the cycle of financial scarcity, you already have the capabilities. It’s just a matter of making the investment.
Image: iamhogir; Pexels