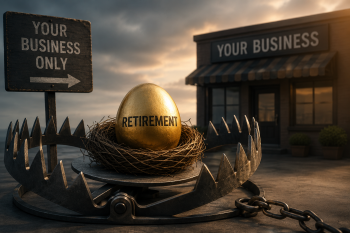
We’ve been sold on the myth that going “all-in” is the only way to build an empire. So we drain our bank accounts and invest every profit back into the company. We tell ourselves it’s “ambition,” but it’s often just bad money habits masquerading as hustle culture.
For too many founders, though, endless reinvestment is a trap. We treat it like a badge of honor. Even after decades of building a company that looks impressive on paper, you may have less cash in the bank than a recent college graduate. You haven’t built a legacy. Instead, you’ve built a fragile house of cards.
I call this the retirement trap. It’s the belief that your business is your 401(k), your pension, and your legacy. In other words, it assumes if you feed the beast enough, it will eventually feed you.
The reality? For many entrepreneurs, this “all-in” strategy is the fastest way to reach age 65 with a massive company on paper and no liquidity. A staggering 80% to 90% of a business owner’s net worth is typically tied to their business, according to the Exit Planning Institute. When your entire income is tied to a single company, you’re not an investor; you’re a hostage to your ambition.
Table of Contents
ToggleThe ROI Delusion
In most cases, the logic behind reinvesting every dollar stems from a perceived Return on Investment (ROI). When you look at the stock market, you see an annual return of 10%. After that, you look at your own company. With $50,000, you could double your revenue by hiring another salesperson or building a marketing funnel.
Investing money in an “uninteresting” index fund seems wasteful to a growth-minded founder. Why would you give your money to Wall Street when you steer the ship?
The problem? ROI isn’t guaranteed, and it’s certainly not diversified. Even though we love to focus on the upside, an estimated 20% of new businesses fail within two years, and roughly half by their fifth year. When you fail to extract wealth along the way, you are basically gambling your retirement on a single point of failure. If you’re one of the 50% who don’t make it to year six, and you’ve reinvested every penny, you’ve lost more than just a job. You’ve lost your entire life savings.
The Valuation Reality Check
I’ve met countless founders who tell me, “My business does $5 million in revenue; at a 5x multiple, I’m worth $25 million. I don’t need a savings account.”
But that thinking has two major flaws.
First, a business is only worth what someone’s willing to pay for it. Market cycles are real. Second, only about 20% to 30% of businesses put on the market actually sell. That means 70% to 80% of owners are stuck with an asset they can’t sell. When you reach retirement age during a recession or a period of high interest rates, your “5x multiple” might vanish, leaving you with an unsellable business.
Second, many small-to-mid-sized businesses suffer from “owner dependency.” In turn, small businesses fail to sell because of a “value gap” — the difference between what the owner believes the company is worth and what the market is willing to pay. The owner is often the business, so this gap exists. Unless your expertise, relationships, and long hours are essential to the company, it’s not an asset — it’s a job. And nobody wants to buy a job.
The Liquidity Crisis
You can’t buy a retirement home in Portugal with equity. And you definitely can’t pay for a medical emergency with “brand equity.”
When an entrepreneur reaches a certain age, they realize they are “cash poor and asset rich.” They have a beautiful office, 50 employees, and a high-profile brand, but their personal bank account doesn’t reflect a decade of work.
According to a BMO Wealth Management survey, 75% of small business owners have less than $100,000 saved for retirement. Even more concerning? According to a SCORE report, 34% of small business owners have no retirement plan.
When your wealth is tied entirely to your business, you can’t handle life’s curveballs. Without liquidity, founders often stay in the game longer than they want to, leading to burnout. Entrepreneurship quickly turns into a prison sentence when you’re forced to work because you do not have any outside savings.
How to Escape the Trap (Without Stunting Growth)
You don’t have to give up on your company to break free of the retirement trap. It means you start treating yourself as a priority stakeholder. Here’s how to balance the spirit of “all-in” with financial prudence.
Take a market-rate salary.
To “help the business,” many founders underpay themselves. Stop doing that. Pay yourself a salary in line with your role. What would you pay a CEO to replace you? That’s your number.
In the end, taking a real salary forces the business to run on its true margins and lets you invest elsewhere.
Max out tax-advantaged accounts.
This is the simplest solution. Whether it’s a SEP IRA, Solo 401(k), or SIMPLE IRA, these tools are designed for us. As a result, you can lower your taxable income while building a nest egg that is legally protected from business creditors. Even if you contribute only the maximum allowed each year, compounding outside of your business is your greatest insurance.
Build for an exit, even if you never sell.
When a business is “ready to sell,” it’s in good shape. This means you have documented processes, a strong team, and clean financials. When you focus on making the business more lucrative and less dependent on yourself, you make it more attractive to outside buyers. Making your business a liquid asset increases the likelihood that, when you’re ready to retire, you’ll be able to cash out.
Diversify your identity.
The retirement trap isn’t only financial; it’s emotional, too. In many cases, entrepreneurs put all their wealth back into their business because it is who they are. They feel like they’ve failed as a person if the business fails.
When you invest in outside interests, such as real estate, angel investing in other startups, or hobbies that aren’t related to your business, you begin to decouple your self-worth from your balance sheet. By diversifying your mind, you can make rational financial decisions about when to take money out of a company.
The Bottom Line
Your business should create the life you want, not consume it.
An “all-in” mentality may work well in stages, but it’s a recipe for disaster in the long run. Today, 90% of owners have their wealth in one basket, and 70% of businesses fail to sell, making the chances of reinvesting everything into a comfortable retirement slim.
Don’t let your passion for your company blind you to the need for financial security. Yes, invest in your growth, but don’t forget to invest in the version of you who wants to retire. Entrepreneurship isn’t just about building a company that changes the world. Ultimately, it’s about creating a lifestyle you can afford to enjoy when the work’s done.
Image Credit: Albert Costill/ChatGPT