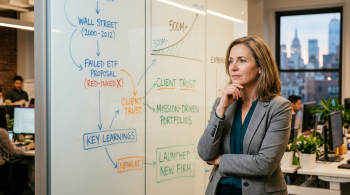
Forbes recognition prompted me to reflect on an unlikely business journey. It began with 12 years on Wall Street, moved through an unsuccessful ETF venture, and led to the launch of LifeGoal Investments. Since then, the firm has raised more than $500 million, far exceeding our original three-year goal.
The Forbes Top Next-Gen Advisor recognition is meaningful. Yet the award tells only part of the story. The path included high costs, poor market timing, closed funds, and a difficult admission that our first idea had failed.
The main lesson is simple: a failed product does not have to end the larger mission. Sometimes, it reveals what clients need and how they prefer to receive it.
Table of Contents
ToggleLeaving Wall Street to Build Something New
I spent about a dozen years working on Wall Street before breaking away. That experience helped shape my view of investing, risk, and financial planning.
It also exposed a common problem. Many sophisticated investment strategies seemed out of reach for ordinary investors. The opportunity was to make useful ideas available through a familiar structure.
That goal led to the launch of five exchange-traded funds, commonly called ETFs. An ETF pools investments into a fund that can trade on an exchange. Investors can buy and sell shares through a brokerage account.
Our aim was to package specialized investment approaches in a form that more people could use. The products were tied to real financial goals rather than abstract market themes.
One was a home-down-payment ETF. It was designed for people saving and investing for their first home. The concept addressed a major concern for many young adults: how to prepare for a large purchase while managing investment risk.
The purpose felt worthwhile. However, the timing created serious challenges.
View this post on Instagram
A Difficult Launch During the 2022 Bear Market
We introduced the ETFs as markets entered the 2022 bear market. Stocks and bonds both faced pressure, while inflation and rising interest rates unsettled investors.
Launching any investment fund requires trust, distribution, and enough assets to cover operating costs. Those demands become harder during a market decline. Investors often grow cautious, while financial advisers may hesitate to adopt an unproven fund.
Our products did not attract enough assets to reach a sustainable size. They were also expensive to operate. Fund administration, legal work, regulatory requirements, trading, and other ongoing duties created costs we couldn’t ignore.
The ideas had a clear purpose, but purpose alone could not make the economics work. The funds failed to scale, and we eventually closed them.
They failed to scale, cost a significant amount to run, and we had to close up shop.
Calling the outcome a failure is uncomfortable, but accuracy matters. The venture did not meet its business goals. Closing the products was the responsible decision once the numbers no longer supported keeping them open.
That experience produced several practical lessons:
- A useful idea still needs strong demand and workable costs.
- Market timing can influence whether a new financial product gains support.
- Investors often value personal guidance more than another product.
- Closing an unsuccessful venture can preserve time and capital for a better model.
Failure also forces a leader to separate ego from evidence. It would have been easy to keep funding the ETFs because of the work already invested. Past spending, however, does not prove that future spending is wise.
Social Media Revealed What People Wanted
While the ETF effort struggled, another part of the business was taking shape. I began sharing financial content on social media in 2021.
The goal was to explain investing and personal finance in direct, useful terms. Over time, followers began asking a question that changed our direction: “Taylor, will you manage my money?”
That feedback pointed to a different need. People weren’t just searching for financial products. Many wanted an ongoing relationship with an adviser who could connect investments to their actual goals.
This distinction matters. A fund may solve one investment problem, but a person’s financial life includes many linked decisions. Clients may need help with retirement, taxes, home purchases, education, cash flow, insurance, and estate planning.
An advisory relationship can place those decisions into one plan. It can also provide support during market downturns when emotions run high.
The audience was effectively giving us market research through repeated requests. Rather than insisting on the first business model, we listened.
Launching LifeGoal Investments
We launched LifeGoal Investments in September 2023. The new business focused on managing client wealth instead of asking investors to adopt a set of newly created ETFs.
Our original target was ambitious. We hoped to raise $100 million over three years. Reaching that level would have demonstrated strong demand and given the firm meaningful scale.
Within roughly three years, the firm had raised more than $500 million. That result was five times the initial goal.
We thought success would be raising $100 million in three years. We have raised more than $500 million, and we are just scratching the surface.
The growth did not erase the ETF failure. Instead, it gave that failure context. The first venture clarified where our skills, audience, and client demand aligned best.
The figures also show why business owners should test their assumptions. We first assumed that wider access to specialized funds was the main opportunity. Client responses suggested that advice and portfolio management were more valuable.
That shift did not abandon the original mission. It changed how we pursued it. We kept the focus on helping people make informed financial decisions, but shifted from products to personal advice.
What the Forbes Recognition Represents
Being named to the Forbes Top Next-Gen Advisor list is a proud moment. Professional recognition can signal that a firm’s work and growth have earned attention within the financial industry.
Still, a ranking should not become the sole measure of success. More important results are whether clients understand their plans, receive useful advice, and feel prepared to make financial decisions.
The recognition also reflects a story that includes setbacks. Public success can look smooth from the outside. In practice, progress often involves wrong turns, difficult choices, and projects that do not survive.
That is why I do not want to present this experience as a simple victory story. The unsuccessful ETF launch is part of the result, not an embarrassing chapter to remove.
It taught us to watch costs, confirm demand, and listen carefully. It also showed that an audience can become a community, and that a community may identify a better business opportunity.
Lessons for Investors and Business Owners
This story offers useful ideas for people outside the financial advice industry. Any entrepreneur can become attached to a product after spending money and time on it. Yet commitment should not replace honest review.
A business model must solve a clear problem at a price that supports continued service. If customers keep requesting something different, their requests deserve attention.
- Listen for repeated questions. Frequent requests may reveal demand that formal surveys miss.
- Measure costs early. A product can attract interest and still fail financially.
- Change direction when evidence supports it. Flexibility is not the same as giving up.
- Keep the mission separate from the method. A method may fail even when the larger purpose remains sound.
- Share setbacks honestly. A clear account of failure can build more trust than a polished success story.
Investors can apply a similar discipline to their own decisions. Judge a strategy by its purpose, risks, costs, and fit with a financial plan. An appealing story is not enough.
People saving for a home, retirement, or another major goal should also consider how soon they’ll need the money. Short timelines may call for a different investment mix than long-term goals.
No award or growth figure changes the duty to put client needs first. As CEO of LifeGoal Wealth Advisors and a Certified Investment Management Analyst and Certified Financial Planner, I keep that responsibility central to my work.
Raising more than $500 million is a milestone worth celebrating. The deeper achievement, however, came from listening to people who asked for help and then building a service around that request.
I am proud of what our team built, but the result belongs partly to the clients and followers who guided the shift. Their questions helped turn a failed fund business into a growing advisory firm.
The clearest recommendation is to treat setbacks as information. Review the facts, protect the people who rely on you, and stay willing to change your approach. A failed launch may close one route while revealing a more useful one.
Frequently Asked Questions
Q: Why were the five ETFs closed?
The funds launched during the difficult 2022 bear market and didn’t attract enough assets. Their operating costs were also too high for their size, so closing them became the responsible choice.
Q: What led Taylor Sohns to start an advisory firm?
After Taylor began publishing financial content in 2021, followers repeatedly asked him to manage their money. Those requests showed demand for personal advice and ongoing portfolio management.
Q: How did the firm perform against its first growth target?
The initial goal was to raise $100 million within three years. Over that period, the firm raised more than $500 million, about five times the original target.
Image Credit: Pexels